
In a rear end collision, the driver who hit you from behind is usually presumed to be at fault. Every driver is expected to keep a safe distance and be able to stop in time. That makes rear end claims some of the most straightforward car accident claims there are. But “usually” is doing a lot of work in that sentence, and insurers still find ways to reduce what they pay.
Rear end crashes are among the most common types of collisions on American roads. Many happen at low speeds in traffic, and many leave people with neck and back injuries that don’t feel serious at first. Here is how these claims work, the exceptions to the fault rule, and how to make sure you are paid fairly.
Why the Rear Driver Is Usually at Fault
Traffic laws in every state require drivers to follow at a distance that lets them stop safely. If you are hit from behind, the natural conclusion is that the other driver was following too closely, wasn’t paying attention or was going too fast for conditions.
In many states this creates what is called a presumption of negligence. The rear driver can try to overcome it, but the starting point favors you. Common causes of rear end crashes include:
- Texting or looking at a phone
- Tailgating
- Speeding in heavy traffic
- Driving while tired or impaired
- Not adjusting to rain, snow or ice
- Misjudging a light changing to yellow
When the Front Driver Can Share the Blame
The presumption isn’t absolute. The rear driver’s insurer may argue that you contributed to the crash if:
- Your brake lights weren’t working
- You suddenly reversed
- You cut in front of the other car and braked hard
- You stopped suddenly for no reason, sometimes alleged in staged accident cases
- You were stopped in a travel lane without hazard lights after a breakdown
If any of these come up, evidence becomes important. A dashcam, a witness or photos of working brake lights can shut down these arguments quickly. In most states, even if you are found partly at fault, your recovery is reduced by your share rather than wiped out.
Chain Reaction Crashes
When three or more cars are involved, fault gets more complicated. If a car slams into the back of the line and pushes everyone forward, the last driver is often responsible for most or all of the damage. But if the middle driver was also following too closely and would have hit you anyway, they may share responsibility. In these cases, you may need to claim against more than one insurer.
Common Rear End Collision Injuries
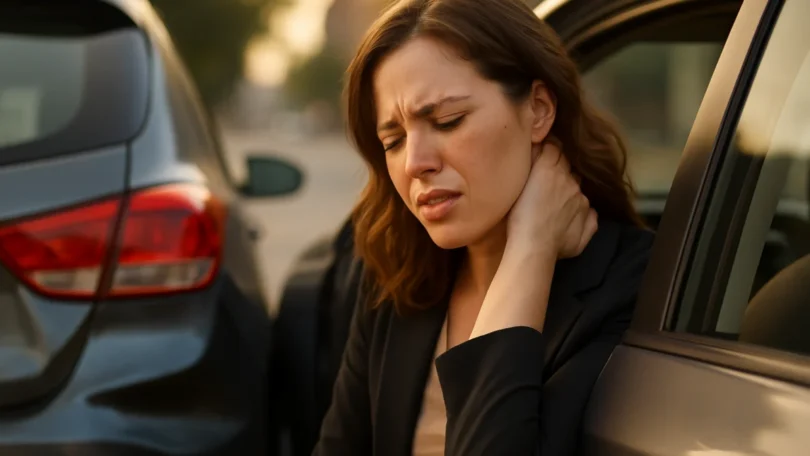
Even a low speed impact can throw your head and body forward and back faster than your muscles can react. Common injuries include:
- Whiplash and other neck sprains and strains
- Back injuries, including herniated or bulging discs
- Concussions, sometimes from hitting the headrest or steering wheel
- Shoulder injuries from the seatbelt
- Wrist and hand injuries from bracing on the steering wheel
- Facial injuries from airbags
Many of these injuries don’t show up right away. It is common to feel shaken but fine at the scene and wake up stiff and sore the next day. That delay is normal, but it is also something insurers try to use. Seeing a doctor within a day or two creates a clear connection between the crash and your symptoms.
The “Low Impact” Argument
If your car has only a small dent or scratched bumper, expect the insurer to argue that the crash was too minor to cause real injury. Some insurers have special units for what they call minor impact soft tissue claims, and they tend to offer very little.
Here is the problem with that argument: modern bumpers are designed to absorb impact without visible damage, which means the force can transfer to the people inside instead. Visible damage is not a reliable measure of injury. Your medical records, symptoms and treatment are what matter. Still, low damage claims are harder to negotiate, so good documentation matters even more.
What You Can Recover
| Type of damage | Examples |
|---|---|
| Vehicle damage | Repairs, or market value if the car is totaled |
| Rental car | A comparable vehicle while yours is being fixed |
| Medical costs | ER, urgent care, imaging, doctor visits, physical therapy, chiropractic care, medication |
| Lost income | Missed work, used sick days, lost overtime |
| Pain and suffering | Physical pain, sleep problems, stress, activities you couldn’t do |
| Diminished value | Loss in resale value after major repairs, where allowed |
If you live in a no fault insurance state, your own personal injury protection coverage pays your medical bills first, regardless of fault. You can usually only claim pain and suffering against the rear driver if your injuries meet your state’s threshold.
Step by Step After Being Rear Ended
- Check for injuries and call 911 if anyone is hurt.
- Move to safety if the cars can be driven and it is safe to do so.
- Call the police and ask for a report number.
- Take photos of both cars, especially the front of the other car and the back of yours, plus the road and traffic signals.
- Exchange information with the other driver. Don’t apologize or discuss fault.
- Get witness names and phone numbers.
- See a doctor within 24 to 48 hours even if you feel okay.
- Notify your insurer and open a claim with the other driver’s insurer.
- Keep records of every bill, receipt and missed work day.
Dealing With the Rear Driver’s Insurer
Because fault is usually clear in a rear end crash, many insurers accept liability fairly quickly for the property damage. The fight tends to be over injuries. Expect the adjuster to:
- Ask for a recorded statement about how you feel
- Request access to your full medical history
- Question any gap in your treatment
- Suggest your pain came from something else
- Offer a small settlement early
You can keep your communication short and factual, share only records related to the crash, and wait to settle until you know how your injuries are healing.
How Much Are Rear End Claims Worth?
There is no standard amount. Minor soft tissue claims with a few weeks of treatment often settle for modest amounts, sometimes a few thousand dollars to the low tens of thousands, depending on medical costs and where you live. Claims involving herniated discs, injections, surgery or concussions can be worth much more.
The factors that matter most are your total medical bills, how long you were in treatment, whether imaging shows objective injuries, how much work you missed, how the injury affected your daily life, and the at fault driver’s insurance limits.
How Long Rear End Injuries Take to Heal
Recovery time varies a lot. Many mild neck and back strains improve within a few weeks with rest and therapy. Others linger for months, especially when there is disc involvement or nerve irritation. A smaller group of people develop chronic pain that lasts a year or longer.
That uncertainty is exactly why settling early is risky. A claim settled two weeks after a crash assumes you will get better quickly. If you don’t, you will be paying for ongoing treatment yourself. Most injury lawyers recommend waiting until you reach maximum medical improvement, the point where your doctor says your condition has stabilized, before agreeing to a final number.
Your Own Policy Can Help Right Away
While the rear driver’s insurer evaluates your injury claim, your own coverage may help in the meantime. Medical payments coverage, often called MedPay, pays medical bills regardless of fault in many states. Collision coverage can fix your car quickly, and your insurer will usually try to recover your deductible from the other company. Check your policy or call your agent to see what you have. Using your own coverage for a not at fault accident generally shouldn’t raise your rates in most states, but ask to be sure.
A Quick Example
Kayla is stopped at a red light in Columbus when a driver looking at her phone hits her at about 20 miles per hour. Kayla’s bumper needs replacing. She feels fine that evening but wakes up with a stiff neck and headache. She goes to urgent care that day, then starts physical therapy. An MRI later shows a bulging disc in her neck.
The other insurer first offers $4,000, pointing to the modest damage. Kayla keeps going to therapy, documents her headaches and missed work, and waits until her doctor says she has stabilized. Her final demand includes all her treatment costs, lost wages and a detailed account of how the injury affected her work and sleep. The settlement ends up several times higher than the first offer. Patience and records made the difference.
Mistakes That Lower Rear End Settlements
- Telling the officer or the other driver “I’m fine” at the scene
- Waiting a week or more to see a doctor
- Skipping physical therapy sessions
- Posting workout or vacation photos during recovery
- Settling before your doctor knows if you will fully recover
- Giving a long recorded statement to the other driver’s insurer
Staged Rear End Accidents
A small number of rear end crashes are staged by fraud rings. A typical scheme involves a car suddenly braking in front of you for no reason, sometimes after cutting in. The people inside then claim injuries. If you rear end someone and something feels off, such as a sudden stop with no traffic ahead or passengers who immediately complain of pain, note the details and tell the police and your insurer. If you are the driver who was hit, this is also why insurers sometimes look closely at rear end claims. Good documentation helps show your claim is genuine.
When to Get Legal Help
A simple rear end claim with minor injuries can often be handled directly. Talk to a lawyer if your injuries require ongoing treatment, if the insurer is arguing that the crash was too minor to hurt you, if fault is being disputed, or if multiple cars were involved. Free consultations let you find out whether legal help is likely to increase your recovery.
What to Do Next
If you were just rear ended, get checked by a doctor even if you feel okay, file a police report and start collecting your bills and photos. Don’t let a small dent convince you or the insurer that your injuries don’t count. Rear end claims are among the most winnable claims out there, as long as you protect them from the start.
Sources
- NHTSA: Traffic Safety Facts
- Insurance Institute for Highway Safety: Rear Crashes
- Insurance Information Institute
This article is for general information only and is not legal advice. Laws change and every case is different, so speak with a licensed attorney in your state about your own situation.
Frequently Asked Questions
Is the driver who rear ends you always at fault?
Usually, but not always. The front driver may share fault if their brake lights didn’t work, they reversed, or they cut in and braked suddenly.
Can I get money for whiplash from a rear end collision?
Yes. Whiplash is one of the most common rear end injuries, and its medical costs and pain and suffering can be part of your claim.
What if there is barely any damage to my car?
You can still be injured. Insurers often use low damage to argue against injury claims, so medical documentation is especially important.
How long after a rear end accident can you feel pain?
Pain often appears within 24 to 72 hours, sometimes later. See a doctor as soon as symptoms appear.
Who pays in a chain reaction rear end crash?
Often the last car that started the chain, but middle drivers may share fault if they were following too closely.
Should I accept the first settlement offer?
Usually not before your treatment is finished. Early offers rarely account for the full cost of your injuries.
Will my rates go up if I was rear ended?
In most states, insurers aren’t supposed to raise rates for an accident you didn’t cause. Rules vary, so ask your insurer how they handle not at fault claims.